The latest Producer Price Index (PPI) report showed a pickup in producer prices in August, with final demand prices increasing 0.4% following a 0.1% increase in July. Final demand goods prices rose 1.1%, while final demand services increased a more modest 0.1%. While the headline increase was notable, the details of the report provide a better picture of where price pressures are coming from.
The PPI measures the average change over time in the prices producers receive for goods and services. This differs from the Consumer Price Index (CPI), which measures prices from the perspective of consumers. Because PPI looks at prices earlier in the production process, it can provide insight into some of the cost pressures businesses are facing before those pressures potentially reach consumers.
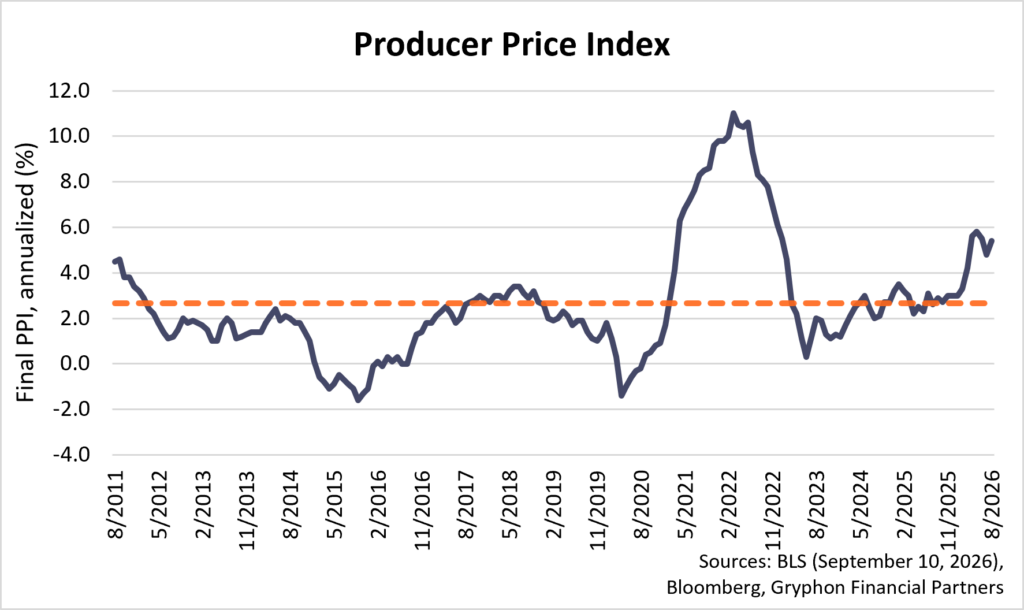
Producer Prices Increased in August
Final demand prices increased 0.4% in August, bringing the year-over-year increase to 5.4%. The monthly increase was primarily driven by goods, with final demand goods prices rising 1.1%. Final demand services increased a more modest 0.1%.
The distinction between goods and services is important when interpreting the report. Goods are physical products, while services include activities such as transportation, healthcare, financial services, and other business services. The August data show that the increase in producer prices was concentrated more heavily in goods, although services prices also rose. This distinction matters because goods prices can be more sensitive to energy costs, supply-chain disruptions, and commodity markets, while services prices are often influenced by wages, demand, and operating costs. Services inflation can also prove more persistent because labor and other operating costs tend to adjust gradually. Looking at both categories helps clarify whether price pressures are broad-based or concentrated in specific parts of the economy.
Goods and services can affect the economy in different ways. Goods prices are often more exposed to changes in energy, commodity, and supply chain costs, while services prices tend to reflect labor costs, transportation, and business operating expenses. Looking at the two categories separately helps show whether producer price pressures are broad-based or concentrated in a few areas.
Goods Inflation Was Driven by Energy
Final demand goods prices increased 1.1% in August, with energy accounting for more than three-fourths of the monthly increase. Final demand energy prices rose 4.2%, led by a 24.1% increase in diesel fuel prices. Gasoline, jet fuel, and home heating oil prices also moved higher during the month. Food prices were much more stable, increasing 0.1%. Excluding food and energy, final demand goods prices increased 0.4%. This suggests that energy was the largest driver of the monthly increase, although there was still some upward movement in other goods prices.
Services Were More Stable
Final demand services prices increased 0.1% in August, marking the third consecutive monthly increase. The smaller increase compared with goods prices suggests that producer price pressures were more limited across the services side of the economy.
However, individual components of services moved in different directions. Transportation and warehousing prices increased 2.3%, with truck freight prices rising 2.0%. Higher transportation costs can be important because they affect the movement of goods throughout the economy and can add to costs for businesses further along the supply chain. At the same time, trade services declined 0.2%. Trade services measure changes in the margins businesses receive when selling goods, rather than the underlying price of the goods themselves. Services excluding trade, transportation, and warehousing were unchanged during the month. As a result, the overall services increase remained relatively limited despite the strength in transportation-related prices.
Looking Beyond the Headline
While the headline PPI number is useful, it is also important to look at measures that remove some of the categories that can experience larger swings from month to month. Final demand less foods, energy, and trade services increased 0.3% in August after rising 0.4% in July.
This measure is up 4.7% over the past year. Looking at it alongside the headline PPI helps put August’s increase into perspective. Energy prices were a significant reason for the 0.4% monthly increase, particularly because of the sharp move in diesel fuel. However, prices outside of food, energy, and trade services also continued to increase.
The report also showed continued price increases further back in the production process, which is important because higher input costs can eventually put pressure on businesses’ profit margins or lead to higher prices for consumers. Prices for processed goods for intermediate demand increased 1.8% in August and are up 11.5% over the past year. Intermediate demand measures prices for goods and services that are used as inputs to produce other goods and services. These figures provide another indication that businesses continue to face higher costs in parts of the supply chain.
What This Means for Investors
The August PPI report presents a mixed picture of producer price pressures. While the monthly increase was driven in large part by more volatile categories, particularly energy, prices outside of food, energy, and trade services also continued to move higher. This suggests that the increase was not entirely isolated to energy, although the broader price environment remains less pronounced than the headline figure may initially suggest.
For investors, higher producer prices can matter for the economic outlook because businesses may face a choice between absorbing higher costs or passing some of those costs along to customers. If elevated input costs persist, they could put pressure on corporate margins or contribute to higher consumer prices, while also complicating the outlook for interest rates.
Disclosure
This material is provided by Gryphon Financial Partners, LLC (“Gryphon”) for informational purposes only. It is not intended as a substitute for personalized investment advice or as a recommendation or solicitation of any particular security, strategy, or investment product. Facts presented have been obtained from sources believed to be reliable, though Gryphon cannot guarantee their accuracy or completeness. Gryphon does not provide tax, accounting, or legal advice. Individuals should seek such guidance from qualified professionals based on their specific circumstances.